The first year of retirement marks a brand-new beginning. With thousands of people retiring every day, many face the opportunity to rediscover and redesign their lives.
Renée Collins, CEO of retirement services firm RetireReady, emphasizes that the first year of retirement is one of the most critical periods financially and emotionally. She notes that it is not just about leaving a job, but about building a new identity, daily routine, finances, and relationships.
Experts agree that the opening year dictates the decades to come. For a 65-year-old couple, there is a 50% chance one partner will live to 90, and a 20% chance of reaching 100. Because advancements in medical technology have extended lifespans, retirement planning must be approached as a multi-decade strategy rather than a short-term transition.
Bill Gates famously stated, “People overestimate what they can do in a year and underestimate what they can do in a decade.” The initial years of retirement represent the pivotal moment to draft a comprehensive ‘Act II’ blueprint covering preparation, social connections, and life purpose. While this period often triggers the ‘go-go phase’—heavy spending on travel, leisure, and bucket lists—it is essential to establish solid benchmarks for the decades ahead.
Financial Strategies and Avoiding Overspending
According to the Bureau of Labor Statistics’ 2024 consumer expenditure survey, average annual spending for those aged 65 to 74 is $65,149, but drops nearly 20% to $53,031 after age 75. Establishing poor spending habits early can jeopardize a lifetime of savings.
Collins warns that it is easy to fall into overspending when receiving a lump sum from pensions or a 401(k) right after retiring, but spending without a long-term plan is difficult to reverse.
To prevent this, experts recommend implementing a bucket strategy during the first year. Holding 12 to 18 months of living expenses in cash or low-risk assets helps weather market volatility while preserving long-term investments.
Conversely, a lack of guaranteed cash flow in early retirement can trigger behavioral biases that cause retirees to excessively withhold spending.
Financial anxiety remains a dominant concern. A recent Allianz Life survey revealed that 64% of respondents fear running out of money more than death, while 70% of Generation X (born 1965–1980) worry about depleting their retirement funds.
However, falling entirely into a restrictive ‘preservation mode’ has drawbacks. Early retirement is often the only window for specific experiences and goals, and sacrificing all of them strictly for financial preservation is not always ideal.
Managing Travel Expectations and Routine
Travel is widely considered the top priority for the first year of retirement, with 63% of older adults citing it as a primary goal. Yet, reality often falls short. According to a joint report by Age Wave and Merrill Lynch, over 40% of retirees fail to travel as much as planned due to health issues, fatigue, and complex itineraries. Airports, flight delays, and unfamiliar environments can turn leisure into exhaustion.
The solution lies in adjusting expectations to reality—swapping long-haul trips for shorter journeys and prioritizing flexible schedules and comfortable destinations.
Beyond money, structuring purpose and routine is vital. Dana Anspach, CEO of retirement financial planning firm Sensible Money, points out that individuals who retire voluntarily for positive reasons enjoy stable mental health, whereas forced retirees suffer higher rates of depression.
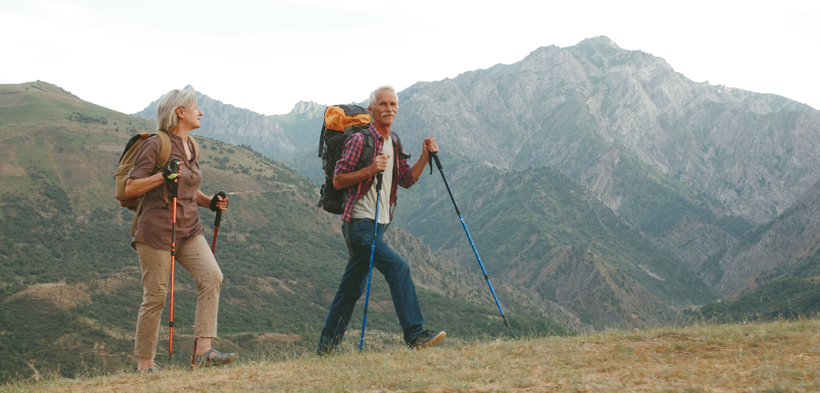
Anspach advises using the first year to try new activities, take on challenges, and discover what brings energy. Actively joining new groups and maintaining social connections is crucial, as social isolation damages both physical and mental well-being.
A rhythmic, structured daily routine prevents days from slipping away aimlessly. Anspach explains why many return to work within 1 to 2 years of retiring: of the 2.4 million pandemic-era retirees, 1.5 million re-entered the workforce by 2022, driven largely by boredom rather than financial necessity.
A 2024 survey by MassMutual showed that while 67% of retirees feel happier than they did during their working years, 8% feel less happy—often due to boredom, which 16% of older adults reported experiencing.
To combat this, picking up a part-time job, volunteering, or engaging in a simple side hustle can easily inject vitality into daily life.
Without a daily commute, physical activity often declines sharply. The U.S. National Library of Medicine defines reduced physical activity and sedentary habits as primary risk factors for chronic illnesses. Incorporating simple habits like a daily 15-minute walk or a weekly activity with friends helps ward off lethargy.
Nurturing Relationships and Embracing New Beginnings
According to a Transamerica Center for Retirement Studies report, 79% of retirees still feel a sense of purpose, meaning 1 in 5 do not. For those whose identity was tied to their careers, the disappearance of daily responsibilities can bring sudden emptiness. Volunteering and meaningful work are proven antidotes to depression and loss of purpose.
Even the closest marriages require attention. Couples spending more time together often experience friction; Psychology Today notes that marital satisfaction tends to dip post-retirement. Finding individual hobbies and communicating feelings openly are essential to navigating this transition.
Ultimately, retirement is not an end but a new beginning. Unforeseen challenges are natural. By preparing financially, emotionally, and socially—and treating initial missteps with flexibility—retirees can turn their golden years into a deeply enriching chapter of life.